LOG-IN
 Important Links/Sites

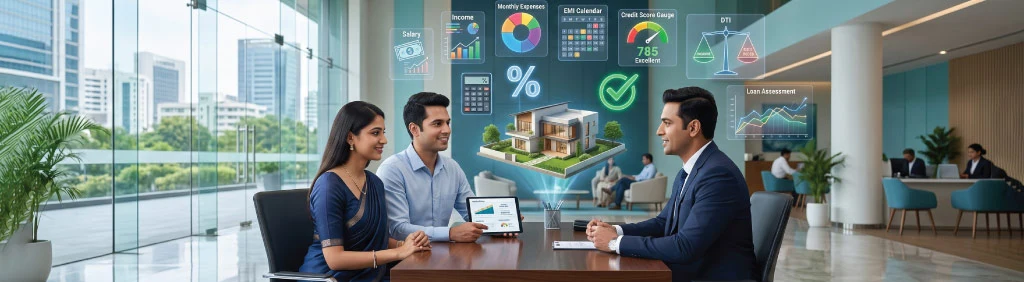
Buying a home is a major milestone. Whether it is your first apartment or a bigger space for your growing family, applying for a home loan is often the first serious financial commitment you make. During this process, you may come across a term called FOIR. If you are planning to apply for a home loan with the Bank of Maharashtra, understanding FOIR can help you prepare better and improve your chances of approval.
Let us break it down in the simplest way possible.
Understanding FOIR and Why It Matters
FOIR stands for Fixed Obligation to Income Ratio. In simple terms, it is a measure that banks use to evaluate how much of your monthly income is already committed to paying existing debts.
Think of it this way. If your income is a pie, FOIR tells the bank how much of that pie is already sliced and allocated to EMIs, credit card bills, and other loan repayments. The smaller the portion used up, the more comfortable the bank feels about giving you a new home loan.
When you apply for a home loan, the Bank of Maharashtra assesses your repayment capacity. FOIR plays a central role in this evaluation because it reflects your financial discipline and ability to handle additional debt.
How FOIR Is Calculated in Home Loans
The formula for FOIR is straightforward:
FOIR = Total Monthly Fixed Obligations ÷ Gross Monthly Income × 100
Let us understand this with an example.
Suppose your gross monthly income is Rs. 80,000.
You are already paying:
- Rs. 10,000 as a car loan EMI
- Rs. 5,000 towards a personal loan
- Rs. 3,000 as minimum credit card dues
Your total fixed monthly obligations add up to Rs. 18,000.
FOIR = 18,000 ÷ 80,000 × 100 = 22.5 percent
This means 22.5 percent of your income is already committed to existing liabilities.
Banks generally prefer a lower FOIR because it indicates that you have enough disposable income to comfortably manage a new home loan EMI.
What Is a Good FOIR for a Home Loan
While exact limits may vary based on income profile and internal credit policies, most banks in India are comfortable with a FOIR ranging between 40 percent and 50 percent. For higher income groups, this limit may sometimes be slightly flexible.
For applicants of the Bank of Maharashtra home loan, maintaining a healthy FOIR improves the chances of:
- Higher loan eligibility
- Faster approval
- Better negotiation on terms
If your FOIR is already close to 50 percent, the bank may either reduce your eligible loan amount or advise you to close some existing loans before applying.
Why FOIR Is Important for Bank of Maharashtra Applicants
When you apply for a home loan, the bank does not look at your salary alone. It evaluates your complete financial picture. FOIR helps the bank answer one key question.
Can this applicant repay the home loan EMI comfortably without financial stress?
For example, two individuals may both earn Rs. 1,00,000 per month. However:
- Applicant A has no existing loans.
- Applicant B is paying Rs. 45,000 in EMIs.
Even though their income is the same, Applicant A has a much stronger repayment capacity. This is exactly what FOIR highlights.
The Bank of Maharashtra follows a structured and transparent evaluation process. By understanding FOIR in advance, you can plan your finances strategically before submitting your home loan application.
How FOIR Affects Your Home Loan Eligibility
FOIR directly impacts three major aspects of your home loan.
Loan Amount Approval
If your FOIR is low, you are likely to qualify for a higher loan amount because you have more repayment capacity.
EMI Affordability
Banks ensure that your total EMIs, including the proposed home loan EMI, do not cross a safe percentage of your income. This protects both you and the lender from financial strain.
Interest Rate and Terms
While FOIR alone does not determine your interest rate, a strong financial profile with a balanced FOIR, good credit score, and stable income can strengthen your overall application.
Practical Tips to Improve Your FOIR Before Applying
If you are planning to apply for a Bank of Maharashtra home loan, here are a few practical steps to improve your FOIR.
Close Small Loans First
If you have a small personal loan or consumer durable loan nearing completion, consider closing it before applying. This reduces your monthly obligations.
Avoid Taking New Credit
Applying for new credit cards or loans just before a home loan application can increase your FOIR and affect your eligibility.
Increase Your Income Proof
If you receive regular bonuses, incentives, or rental income, ensure these are properly documented. A higher documented income lowers your FOIR ratio.
Opt for a Longer Tenure
A longer tenure reduces the EMI amount, which can help maintain your FOIR within acceptable limits.
FOIR and Credit Score Work Together
Many applicants confuse FOIR with credit score. While both are important, they serve different purposes.
- Credit score reflects your repayment history and credit behavior.
- FOIR reflects your current repayment capacity.
Even with a high credit score, a very high FOIR can reduce your loan eligibility. On the other hand, a balanced FOIR combined with a good credit score creates a strong application.
The Bank of Maharashtra considers multiple parameters, including income stability, age, employment profile, credit history, and FOIR, to ensure responsible lending.
Common Mistakes Applicants Should Avoid
When applying for a home loan, avoid these common errors:
- Underestimating existing EMIs
- Ignoring credit card outstanding amounts
- Applying without reviewing financial commitments
- Assuming gross income alone guarantees approval
A little preparation can make a big difference.
Making Your Home Loan Journey Smoother
Understanding FOIR empowers you as an applicant. Instead of waiting for the bank to determine your eligibility, you can calculate your FOIR in advance and take corrective steps if needed.
If you are considering a home loan with the Bank of Maharashtra, reviewing your financial obligations beforehand will help you approach the process with confidence. The bank offers competitive interest rates, transparent documentation requirements, and structured assessment methods that make the journey smoother for applicants.
When you prepare well and maintain a balanced FOIR, you not only improve your chances of approval but also ensure that your home loan remains affordable in the long run.
Conclusion
FOIR in home loans may sound technical at first, but it is simply a way to measure how much of your income is already committed to fixed repayments. A healthy FOIR reflects strong financial discipline and improves your home loan eligibility.
If you are planning to apply for a home loan, take time to assess your current obligations and income. With proper planning and financial awareness, securing a home loan becomes a well-informed decision rather than a stressful process. The Bank of Maharashtra, known for its transparent policies and customer-focused approach, supports applicants at every step, helping you move closer to owning your dream home with clarity and confidence.
Author: Bank of Maharashtra
Date of Publish: 19 Aug, 2026






 Public Information
 Gallery
 Social Activity
 Assets for Sale
 Tenders
 ..